
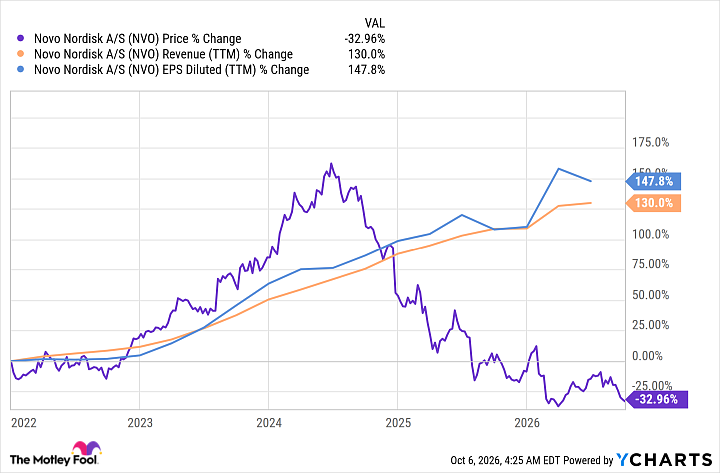
Novo Nordisk (NVO -0.03%) has seen both sides of the emotional swings investors often experience. Enthusiastic investors pushed its stock higher by more than 200% in less than three years. And less than three years after that peak, pessimistic investors have crushed the shares by more than 70%. The stock is now below where it started five years ago.
There are very real reasons for investors to be worried about Novo Nordisk. However, if you are a long-term investor, there are also reasons for optimism. This deep drawdown could very well be a generational opportunity to buy the stock, if you have the stomach for it.
Image source: Getty Images.
Novo Nordisk fumbled the ball
Novo Nordisk is on the back foot when it comes to GLP-1 weight-loss drugs. It was the first to market with its Wegovy drug, but it couldn’t keep up with demand. That gave generics an opening to enter the U.S. market before patent protections ended. When competitor Eli Lilly (LLY +1.26%) brought out a more effective GLP-1 drug, Novo Nordisk became the industry also-ran.
Novo Nordisk has gotten a second chance with its GLP-1 pill, which was brought to market before Eli Lilly’s pill. However, Novo Nordisk announced it would cut the prices of its GLP-1 drugs and focus on volume. The weight-loss market is likely to be huge, so volume is important and may eventually offset the price cuts. However, in the near term, Novo Nordisk’s financial results are likely to be depressed as it shifts its business model around GLP-1 drugs even as the pill version appears to be in high demand.

Today’s Change
(-0.03%) $-0.01
Current Price
$37.53
Key Data Points
Market Cap
Day’s Range
$36.84 – $37.53
52wk Range
$35.12 – $64.16
Volume
13.7M
Avg Vol
12.4M
Gross Margin
80.65%
Dividend Yield
4.79%
Novo Nordisk has to prove it can do more
Eli Lilly is using its GLP-1 success to finance acquisitions that have broadened the company’s business. It now has a materially deeper pipeline of potential drug candidates. Novo Nordisk hasn’t moved as aggressively, with the most notable change being a rebrand to “Novo” to highlight a renewed focus on the company’s future. It didn’t go over particularly well, with many likely viewing it as nothing more than window dressing.

Today’s Change
(1.26%) $14.37
Current Price
$1,157.49
Key Data Points
Market Cap
Day’s Range
$1139.98 – $1177.07
52wk Range
$783.85 – $1292.65
Volume
2.1M
Avg Vol
2.5M
Gross Margin
83.40%
Dividend Yield
0.59%
More recently, the company laid out its plans for multiple new drug releases through 2030. If the company can do that, it will have new drugs on the market before its current GLP-1 drugs start to lose patent protection in the early 2030s. However, it hasn’t shown material success on the development front. Investors are clearly worried, leaving Novo Nordisk in a position where it has to rebuild trust.
Clearly, there’s a lot of negativity around Novo Nordisk, and it is reflected in the pharmaceutical company’s stock decline. However, this is the company that was first to market with a GLP-1 drug and a pill version of a GLP-1, so it has a proven track record in developing new drugs. And given that the price is below its level five years ago, it makes sense to ask whether the company is worse off now than it was then.
Novo Nordisk is likely better positioned than investors believe
Novo Nordisk’s trailing 12-month revenues have grown 130% over the past five years, while trailing 12-month earnings per share have grown 140%. It looks like the healthcare giant is doing something right when you consider those figures. If you are a long-term investor, it probably makes sense to give the company the benefit of the doubt.
Novo Nordisk is moving beyond its historical stronghold in diabetes care, and that has required changes to the company’s business model. The company’s GLP-1 success suggests it has the research and development skills to succeed over the long term. And the still-developing GLP-1 drug market is likely to be huge, with room for more than one winner. If you can stomach some near-term uncertainty, Novo Nordisk is probably more of an opportunity than it is a value trap after its massive 70% drawdown.
