
It’s no secret that the business of college sports is undergoing a significant transformation. Media rights growth, conference realignment, expanded playoff formats, sponsorship activity and institutional investment have contributed to rapidly increasing valuations of major athletic programs.
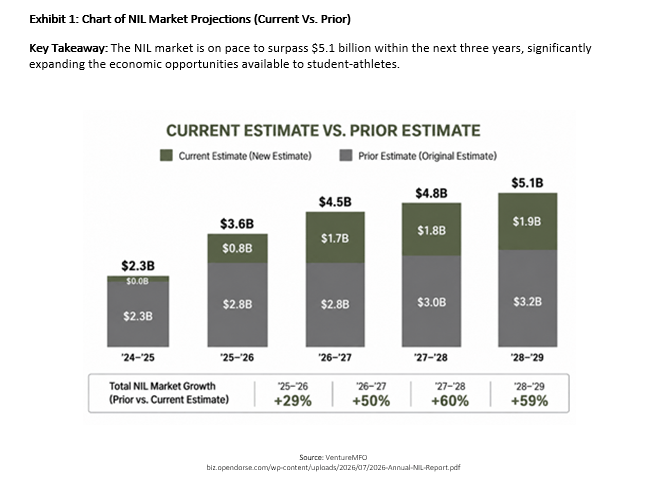
At the same time, name, image and likeness opportunities and new revenue-sharing arrangements are directing a greater share of that economic value to student-athletes. Indeed, the NIL marketplace has grown from approximately $918 million in its inaugural year to an estimated $2.3 billion in 2024–25 and is projected to reach $5.1 billion by 2028–29, according to Opendorse.
With good financial stewardship, this historic transfer of economic value may give select student-athletes an extraordinary opportunity to establish financial independence at an unusually young age. That opportunity is particularly meaningful at a time when the median age of first-time U.S. homebuyers has reached a record 40 years old, according to the National Association of Realtors.
For financial planners, the opportunity extends beyond managing investments. NIL requires a financial plan that accounts for sudden income, uncertain career prospects, tax obligations and family expectations.
For a high-earning NIL athlete, sophisticated planning may eventually be appropriate. The starting point, however, is financial education and a practical framework for managing cash.
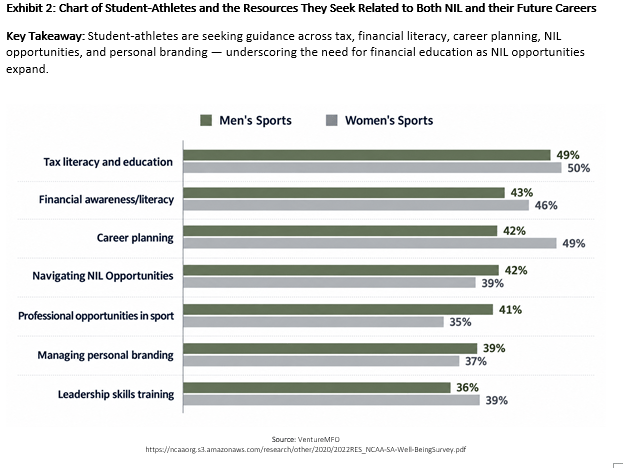
Student-athletes appear to recognize that need. An NCAA survey found that approximately half of surveyed athletes sought resources related to tax literacy and education, while significant percentages also expressed interest in financial literacy, career planning, navigating NIL opportunities, personal branding, and leadership skills
Before introducing complex strategies, planners should help athletes distinguish gross compensation from after-tax cash flow and understand estimated taxes, saving, spending, liquidity and investing.
Consider an athlete receiving a significant NIL payment. Unlike a traditional paycheck, many NIL payments are made without income tax withholding, which means the athlete may be responsible for setting aside funds and making estimated tax payments. For a young athlete, the account balance may therefore appear to be spendable wealth, even though a substantial portion may ultimately be needed for taxes.
The same problem can arise with noncash compensation. An athlete receiving a vehicle, housing or another benefit may have taxable income without receiving the corresponding cash needed to pay the tax. Moreover, athletes may receive income from multiple sources—including revenue sharing, endorsements and other NIL arrangements—each of which may carry different tax, reporting and cash-flow considerations.
Early cash-flow planning is therefore essential. Planners can establish a capital-allocation framework that reserves funds for taxes, separates near-term spending from longer-term capital, and maintains liquidity for unexpected needs. For some athletes, that includes setting spending parameters, or “self-limiting liquidity,” that limit the amount readily available for discretionary purchases while directing the balance toward reserves and long-term investments.
The percentages will differ by athlete, but the framework should be established before spending patterns become entrenched. A practical first step is to map contracted and expected receipts against estimated tax payments, professional fees, living costs, and planned savings, then revisit those assumptions as agreements change.
Those allocations should reflect the athlete’s own priorities, whether purchasing a home, funding education or future ventures, or building long-term wealth. Planners can also distinguish headline compensation from investable capital: A seven-figure earnings year does not necessarily translate into a seven-figure net worth after taxes, fees and spending.
Plan for an Uncertain Earnings Window
For most workers, earnings generally increase over a career lasting several decades. An elite athlete can face almost the opposite pattern.
NIL income may increase rapidly based on performance, marketability and transfer decisions, but it can decline just as quickly because of injury, reduced playing time or changing public interest. Moreover, because an athlete expecting a professional career may never reach it, a significant portion of lifetime athletic earnings may be concentrated into only a few college years.
Consider a hypothetical five-star quarterback who enrolls at a California university at age 19. Following a breakout freshman season, he enters the transfer portal and moves to a Florida program, where his NIL income increases substantially during his sophomore and junior seasons. A career-ending injury during his senior year, however, abruptly ends his playing career.
The planning principle is straightforward: Build the financial plan around the athlete’s values and lifetime goals, not an assumed professional career.
Financial planners can model several career paths before substantial income arrives, including a short earnings window, an interrupted season, or a transition away from sports. Those projections should integrate spending, taxes, entity considerations reviewed with tax counsel, disability coverage, liquidity, and a long-term investment policy. The purpose is not to predict the athlete’s career; it is to make the financial consequences of different outcomes visible.
Capital-allocation and wealth forecasts make those trade-offs concrete. In the hypothetical case study, differences in taxes, spending, and risk management materially change the capital remaining after the playing career ends. Planners should therefore focus not only on expected compensation but also on the portion that can be preserved to support the athlete’s next chapter.
