
Nikola Stojadinovic/E+ via Getty Images
Agree Realty Corporation (ADC) just issued their Q3 2026 earnings release. I wanted to give readers an immediate look inside, so I’m sharing the report we prepared for subscribers. That makes the layout a bit different. We start with the things members want to know. That means foreshadowing any trades and discussing the valuation that goes at the top instead of the bottom.
Bonus Section For People Who Are New
I was about to hit the submit button, but I realized I needed to come back and write this part. Many of my readers on The REIT Forum already know Agree Realty well, so I didn’t spend any time explaining the business. However, I’ll do a quick breakdown for readers who are new to the stock but landed on this article.
Agree Realty is a net lease REIT. Net lease REITs typically have higher than average dividend yields. They typically grow faster than most kinds of net lease REITs when it comes to total revenue and total market cap because their goal is to trade materially above net asset value and then issue shares to fund acquisitions. That’s the strategy. It’s pretty simple. They want to have long-term leases, and they pass the substantial majority of property operating expenses through to the tenant. Because the tenant pays most operating expenses, the business can be pretty simple.
So why does the tenant want that deal? Well, that’s pretty simple. A good net lease REIT like ADC can finance the property much more effectively than the original owner. Often the original owner is the tenant. They simply want to free up their cash, and ADC can own that property and rent it back to them at attractive terms.
ADC trades a higher multiple than most of the net lease REITs, but they’ve also done quite well at growing the REIT, and they keep leverage particularly low. That’s an attractive combination for shareholders, which leads shareholders to give ADC a multiple (or a lower dividend yield if you prefer to think from that angle).
Okay, you understand the stock well enough. Please enjoy.
Foreshadowing & Valuation
I currently do not have a position in Agree Realty. I do not expect to initiate a position in the near future. Shares are trading around the middle of our neutral range (between the buy under level and the overpriced level).
Current positions in net lease REITs:
-
No positions in ADC, Realty Income (O), National Retail Properties (NNN), or W. P. Carey (WPC).
-
Long Four Corners Property Trust (FCPT).
Vocab
-
NTM = Next 12 Months.
-
FFO = Funds from Operations (usually presented as a per share figure).
-
AFFO = Adjusted Funds from Operations (usually presented as a per share figure).
-
NOI = Net Operating Income (rents minus property operating expenses).
-
SS = Same-Store (this compares a pool of properties to themselves a year ago).
- WACC = Weighted-Average Cost of Capital.
AFFO Chart
See the latest chart:
The REIT Forum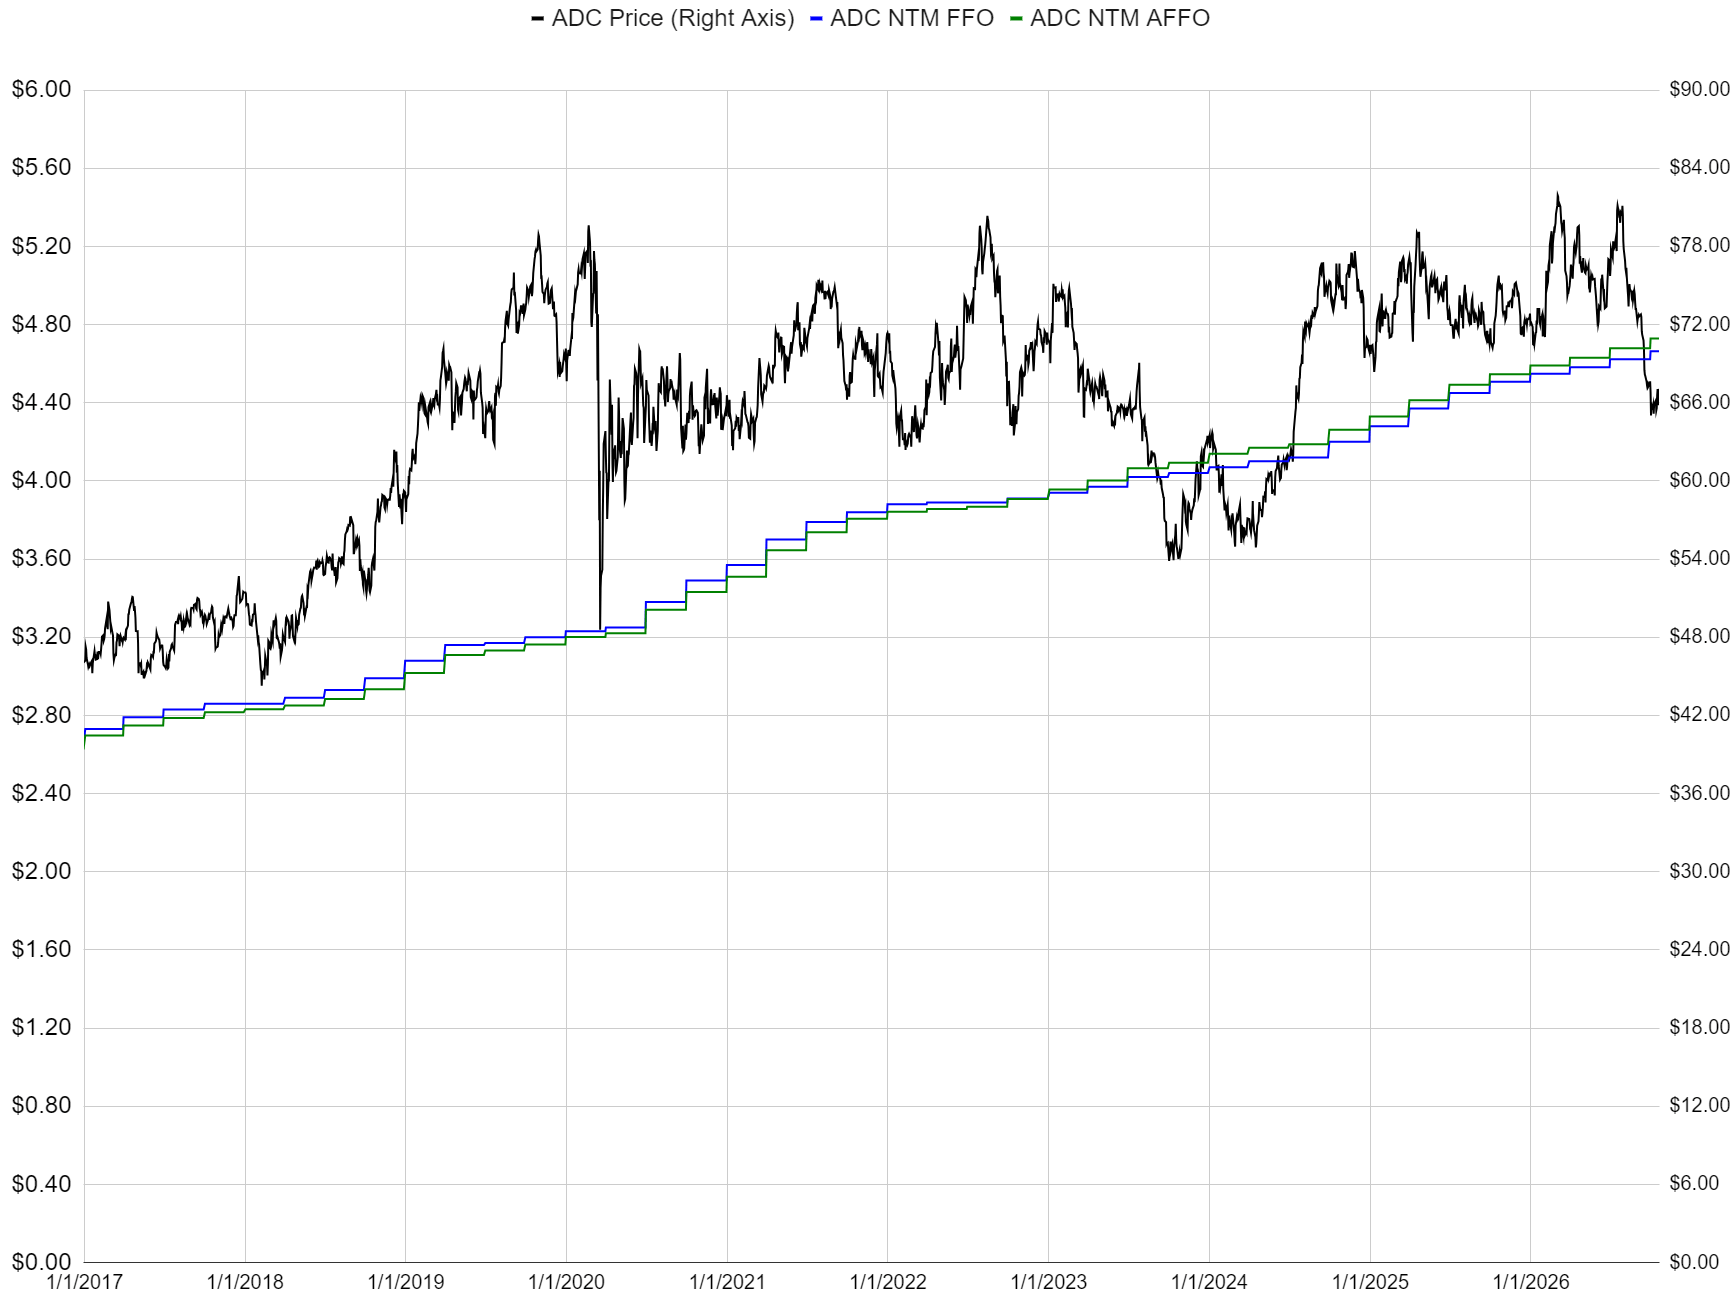
What makes this chart so good? Me. I made the chart. Why does that matter? It isn’t just because I fix some rounding errors. It’s because I do a scan for errors in the data. That doesn’t guarantee that I will catch every error, but I catch quite a few as I do this on the REITs. That means the odds are pretty good that my chart will be accurate.
The Latest Numbers
I don’t like trying to figure out the exact last value in a chart. You probably don’t either. This table provides the latest figures.
The REIT Forum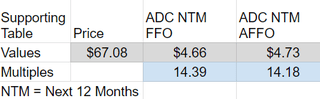
Note: This table includes the benefit of elevated AFFO estimates.
AFFO Multiple
The following chart only uses the more useful values:
The REIT Forum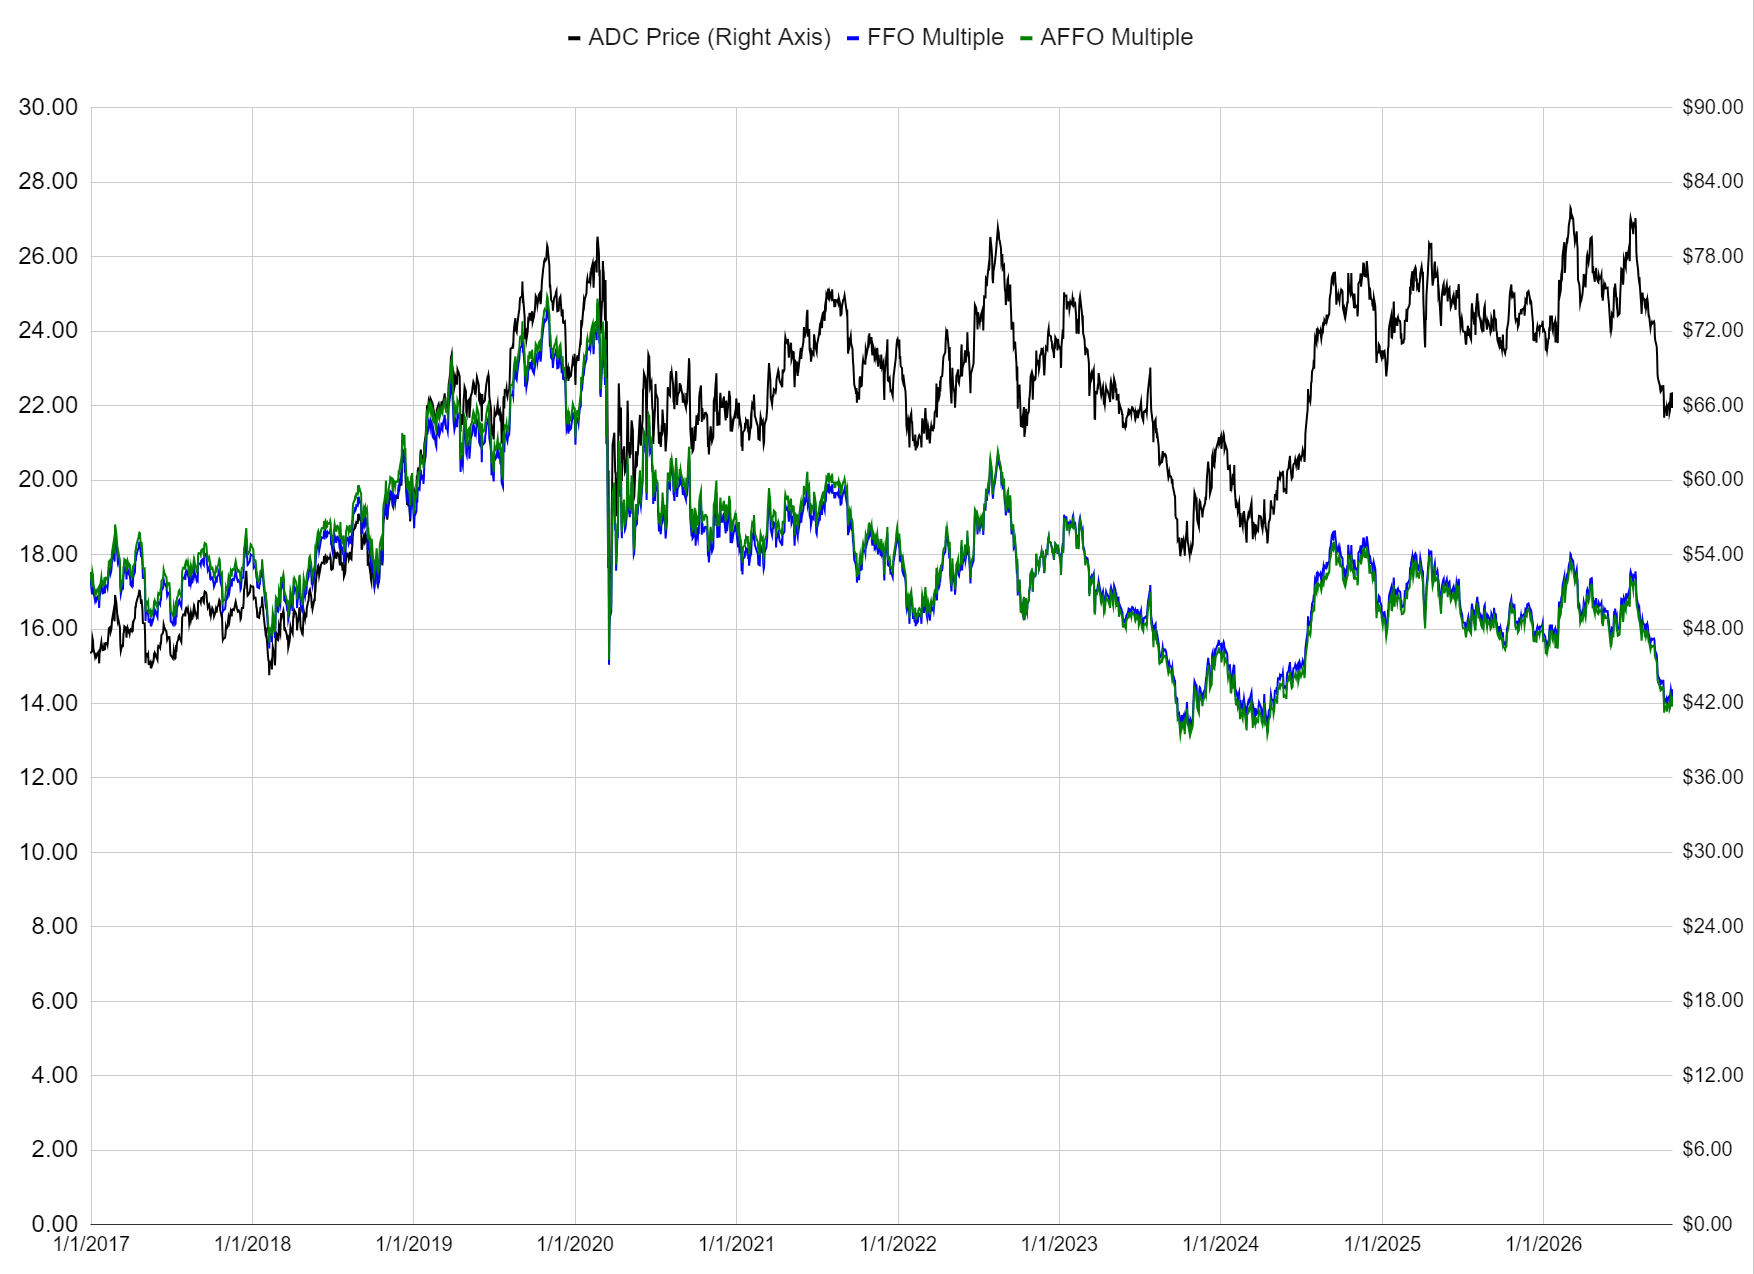
Core FFO and AFFO Results
Agree Realty results:
What’s that? Fractions of a penny? Yes, because using fractions of a penny makes analysis more useful! We can’t always be that precise because sometimes REITs don’t provide enough information.
Here’s the big chart:
The REIT Forum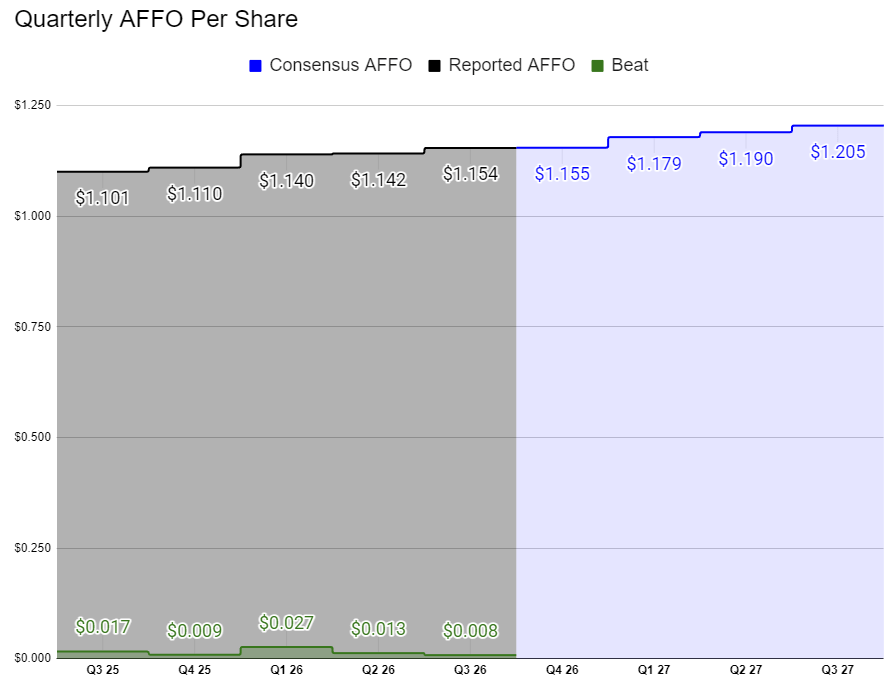
Note: An investor in ADC could use either Core FFO or AFFO. Either is a useful metric. When there’s not a compelling reason to use a different metric for this chart, I default to using AFFO.
Guidance For AFFO
This table puts the results and updated guidance in context.
The REIT Forum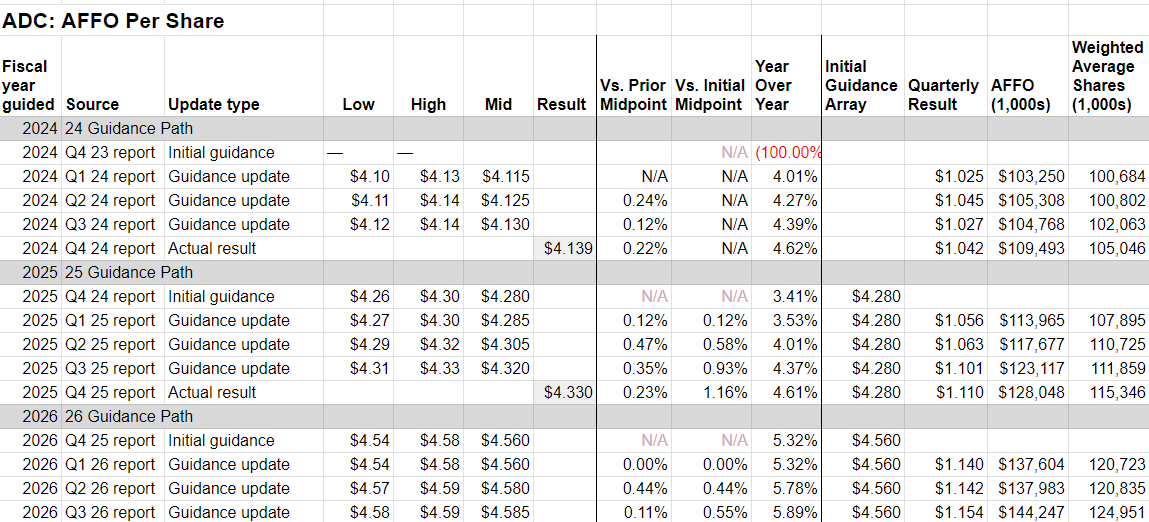
Same-Store Cash Net Operating Income Guidance
ADC typically does not provide guidance on this metric.
Same-Store Cash Net Operating Income Quarterly Result
ADC reports this value as “Same-store Rent Growth.” However, as a net lease REIT, rent and NOI are nearly identical. Consequently, I’m going to keep labeling the slide and section as Net Operating Income.
The REIT Forum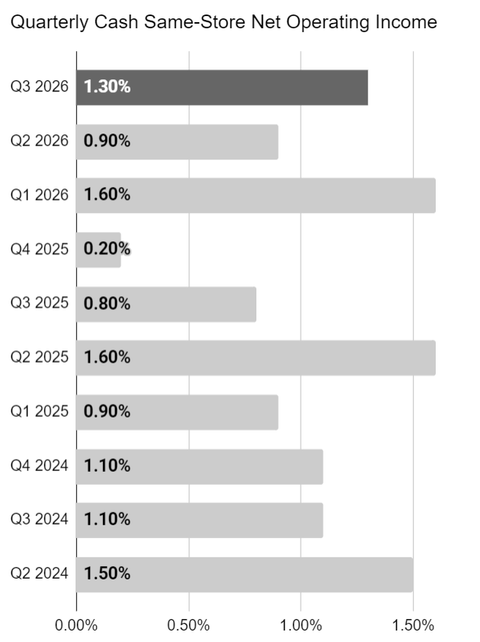
Net lease REITs are not expected to produce significant numbers here. It can happen during periods of inflation when inflation escalators kick in, but most of the time you expect to see numbers around 1%. Or at least it used to be 1%. Given how inflation tends to be higher now, we may see it average a bit higher.
Issuing or Repurchasing Shares
I pulled the numbers from ADC’s table on Forward Equity Offerings and added more columns.
The REIT Forum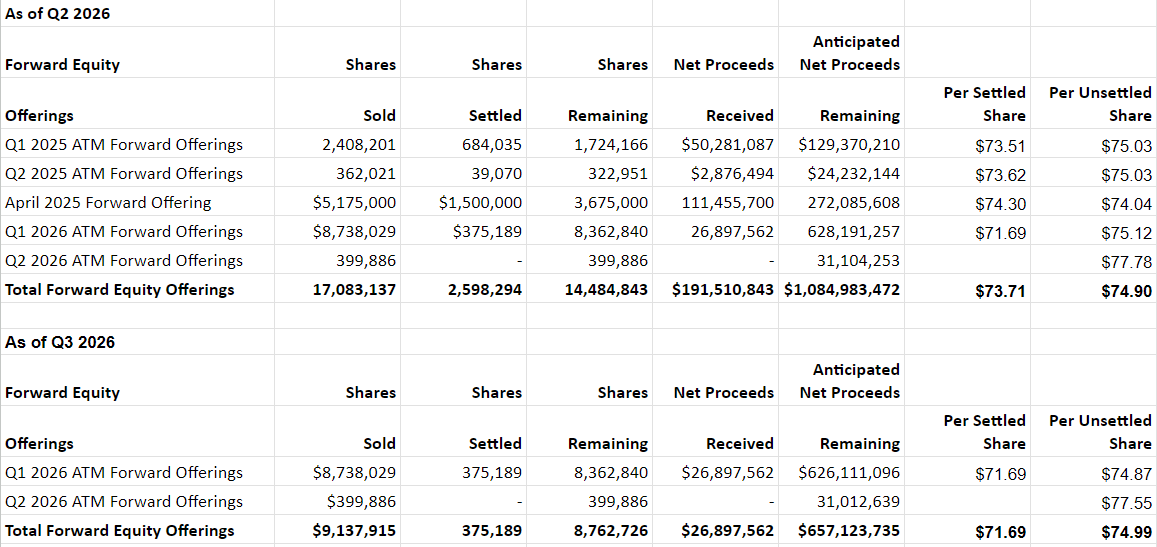
At the end of Q2 2026, ADC still had $1.08 billion left to settle. At the end of Q3 2026, they only have $657 million left to settle. They were not actively entering new ATM forward offerings from the data I saw. So they were settling quite a bit of their outstanding equity.
Acquisitions
These are the key stats for ADC’s acquisitions during Q3 2026:
-
Properties: 68.
-
Total price: $308.6 million.
-
Cap rate: 7.3%.
-
Weighted-average remaining lease term: 14.5 years.
-
Annualized base rent from investment-grade tenants: 52.1%.
Total investment activity, including development and Developer Funding Platform investments, was $357.7 million across 94 properties.
Full-year 2026 guidance for investment volume:
ADC reduced its investment guidance from a midpoint of $1.7 billion to approximately $1.6 billion.
Dispositions
Properties sold during Q3 2026:
-
Properties: 11.
-
Proceeds: $26.9 million.
-
Cap rate: 6.5%.
Full-year 2026 guidance for dispositions:
ADC increased its disposition guidance by $50 million at both ends of the range.
My Notes
ADC put together a pretty good quarter. Nothing amazing, but not disappointing either. They beat the consensus AFFO estimates by a fraction of a penny. At least, that’s how I’m calculating it. I am using actual AFFO and weighted average shares to eliminate rounding errors. I pulled the consensus estimates out to the tenth of a penny.
AFFO per share guidance increased ever so slightly. Not really a material change. The cap rate on those acquisitions at 7.3% easily beats my estimate for ADC’s WACC (weighted-average cost of capital).
If you calculated their cost of capital using the current share price of $67.08, the acquisitions at 7.3% would still be accretive. Using the price they locked in to issue shares, around $75, they are clearing the WACC by a much larger margin. So those acquisitions have been a great choice. Could ADC issue those shares at $75 and repurchase their stock around $67? Yes, but continuing acquisitions is actually a better strategy.
There is one potential negative aspect. Because ADC’s acquisitions have been such a positive factor for shareholders, the reduced guidance on investment volume is a slight disappointment. However, it’s better for ADC to reduce investment volume rather than to accept mediocre deals. Overall ADC has done a very solid job with issuing new shares and expanding the portfolio.
Target Adjustments
None just yet. We did target adjustments for net lease REITs on September 20th, 2026.
Conclusion
The quarter was pretty good. Nothing wild. Results were just a tiny bit ahead of estimates. I don’t see any reason for this to move the price materially. Lately the biggest factor for the stock has been the same thing hitting most equity REITs. A rapid rise in Treasury yields put some pressure on valuations.
